How to Build Credit in the U.S. From Scratch (Even If You Just Moved Here)
A step-by-step guide to building U.S. credit with no history: secured cards, credit-builder loans, using an ITIN, and the mistakes to avoid.
Found a mistake on your credit report? Dispute it for free with Equifax, Experian and TransUnion: what proof to send and what to do if it isn't fixed.
An error on your credit report can lower your score and get you denied for a loan — or charged a higher rate. The good news: in the United States you have the right to dispute inaccurate information, it’s free, and you can do it yourself without paying anyone.
Download your reports from all three bureaus (Equifax, Experian and TransUnion) at AnnualCreditReport.com, the official site. Check all three — each bureau can have different information.
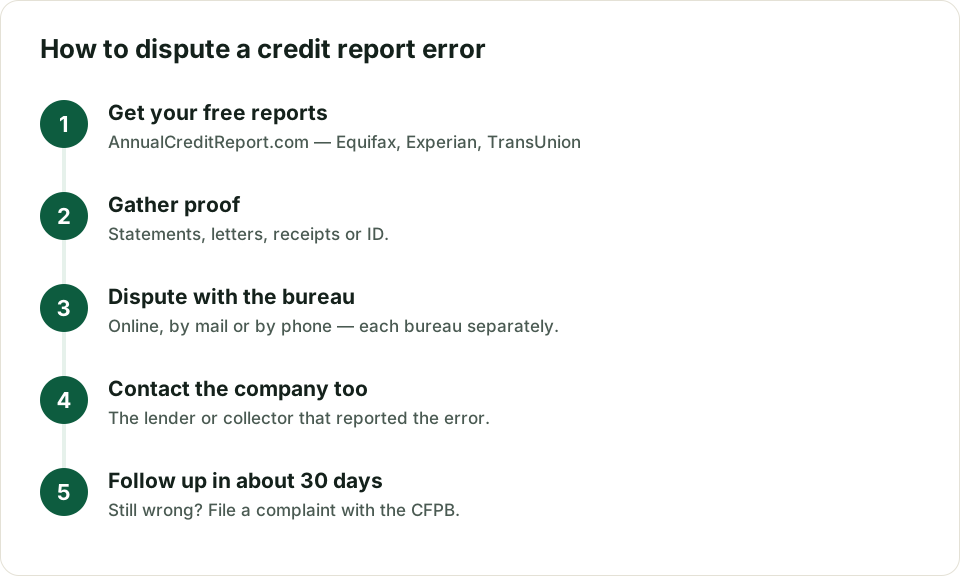
Statements, payment receipts, letters from the lender, ID, or a police report in the case of identity theft. Always send copies, never originals.
File with every bureau that shows the error. You can do it:
Be specific: identify the account, explain the error and say what correction you want.
That’s the bank, card issuer or collection agency that supplied the information (the “furnisher”). If they fix it at the source, it gets fixed at every bureau.
By law, the bureau generally must investigate within about 30 days (it can be extended in some cases) and send you the results in writing. If the information changes, you’ll get an updated copy of your report.
Act quickly:
Negative but accurate information can’t be removed early. In general:
Be wary of “credit repair” companies that promise to erase accurate information for an upfront fee. Anything they can legally do, you can do yourself for free.
Will disputing an error lower my score? No. Filing a dispute doesn’t affect your score. If the error is corrected, your score may go up.
How much does it cost to dispute? Nothing. Disputes with the credit bureaus are free.
How often should I check my report? At least once a year, and always before applying for a big loan like a mortgage or car loan.
If you’re building your history from zero, also read how to build credit in the U.S. from scratch.
This article is for educational purposes only and is not legal or financial advice. Timelines and procedures can change; check official sources from the CFPB and each bureau. Read our Disclaimer.
A step-by-step guide to building U.S. credit with no history: secured cards, credit-builder loans, using an ITIN, and the mistakes to avoid.
How to use a 0% balance transfer card to pay off debt interest-free: fees, promo periods, traps to avoid and a worked example with $5,000.