Personal Loan vs. Credit Card: Which Is Cheaper for a Big Expense?
Borrowing $8,000? We compare a personal loan and a credit card side by side — monthly payment, total interest and fees — so you can pick the cheaper option.
What a debt consolidation loan is, how much you can save with a real $10,000 credit card example, the risks and how to get the best rate.
If you have several high-interest debts — especially credit cards — a debt consolidation loan can help you pay less interest and have one monthly payment. But it isn’t magic: it only works if you change the habits that created the debt.
It’s a personal loan you use to pay off all your other debts at once. From then on you only owe the loan, with:
Say you owe $10,000 on cards with an average APR of 24%, and you’re offered a consolidation loan at 13% APR for 36 months.
If instead you keep paying the same $337 a month on your 24% cards:
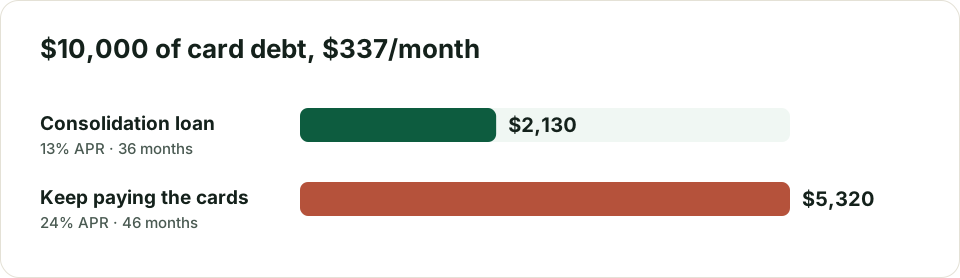
You save about $3,190 and finish 10 months sooner — with the same monthly payment.
Watch out for “debt settlement”: it’s not the same as consolidation. Those companies ask you to stop paying so they can negotiate a discount, which can seriously damage your credit, and many charge high fees.
Will a consolidation loan lower my credit score? It may dip slightly at first because of the hard inquiry and new account. With on-time payments and zeroed-out cards, it usually rises over time.
Should I close my cards after consolidating? Not necessarily — closing them can raise your utilization. If they have no annual fee, keep them and don’t use them.
Can I consolidate student loans? There are specific programs, but be careful with U.S. federal loans: refinancing them into a private loan means losing protections such as income-driven repayment.
This article is for educational purposes only and is not personalized financial advice. Example figures are illustrative; actual rates depend on your credit and the lender. Read our Disclaimer.
Borrowing $8,000? We compare a personal loan and a credit card side by side — monthly payment, total interest and fees — so you can pick the cheaper option.
How to use a 0% balance transfer card to pay off debt interest-free: fees, promo periods, traps to avoid and a worked example with $5,000.